Which one applies to a Smithtown house like yours
The difference between a short sale and a cash sale is who has to say yes. In a cash sale, you and the buyer agree a price and the mortgage is paid off out of the proceeds. In a short sale there is a third party at the table, because the servicer has to accept less than the full balance, and servicers have discretion about that.
We have worked short sales across Nassau and Suffolk for years, and straightforward cash purchases far more often than that. Tell us the payoff on a Smithtown house and we will tell you which conversation you are actually in.
What your lender wants before approving a short sale
Expect adjournments, requests for documents you already sent, and a valuation ordered by the servicer that you will never see. That is the ordinary texture of a short sale rather than a sign yours is going badly.
A short sale also usually runs alongside a foreclosure that does not pause politely while the file is reviewed, which is why starting a short sale early matters so much. Begun late, the short sale and the sale date end up racing each other.
Why local knowledge changes the number
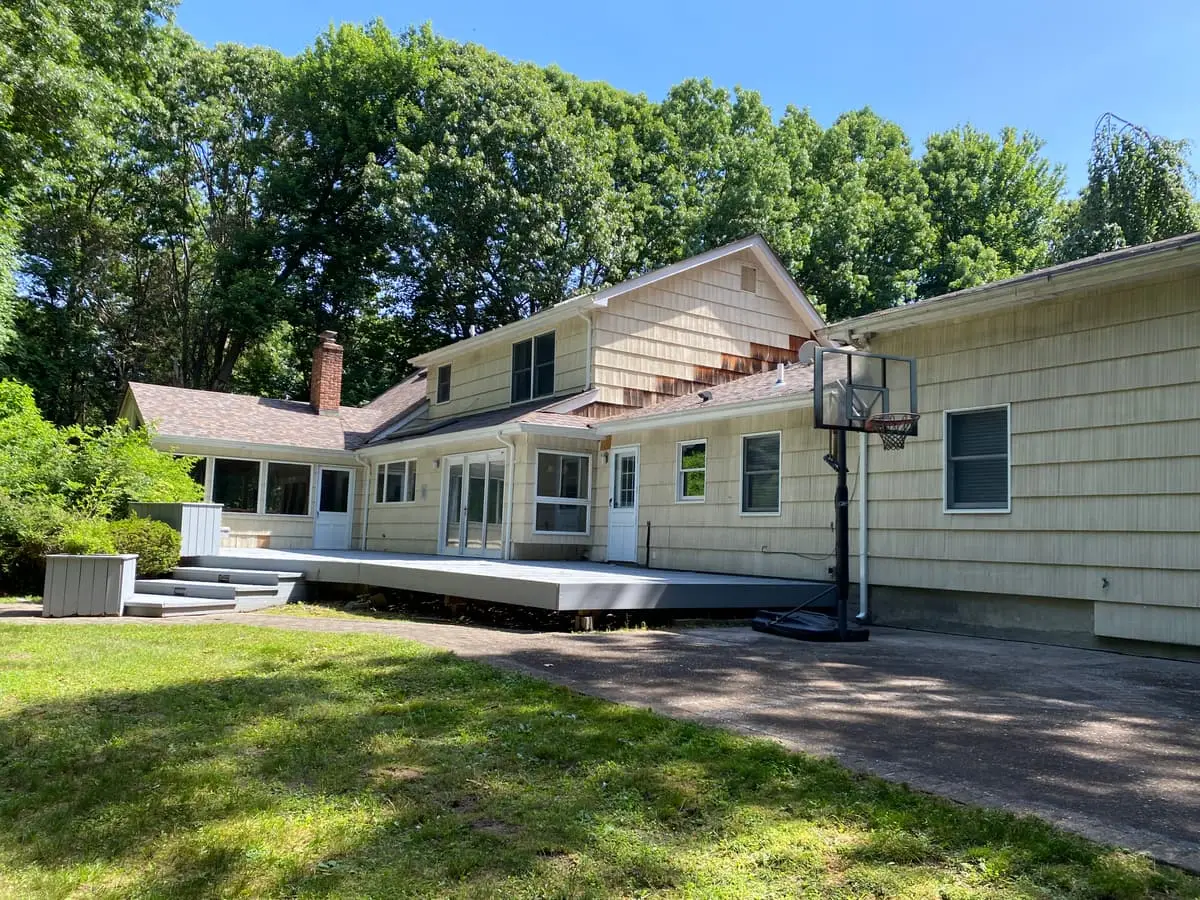
A house on Kent Place. In Smithtown, bought and paid for by us.
Smithtown is roughly 25,629 people in Suffolk County, ZIP 11787, and the housing stock is mostly colonial, split-level, ranch. Around Main Street and the Smithtown Bull, most of it is old enough that the mechanicals are on their second or third life. The Smithtown stop pulls buyers who commute, which supports the good houses and does very little for the ones that need a roof. We have been buying across Suffolk County for 15+ years. We know what the Smithtown Central School District does to a resale price, which blocks still have oil tanks in the ground, and what a house like yours is actually worth here.
How we work a Smithtown short sale with you
We do not turn underwater sellers away. We have worked a great many short sales across Nassau and Suffolk, and we will work yours with you if that is what the numbers call for.
That means we make the offer, we help assemble the short sale package, we deal with the servicer's negotiator, and we stay in it through the adjournments. A short sale is slower and less certain than a cash sale and we will say so at the start. But an underwater owner with an experienced short sale buyer alongside them is in a far better position than one calling around for somebody willing to try.
Timelines: short sale, cash sale, and a listing in Smithtown
The median house in Smithtown sold for $797,500 and took about 23 days to go under contract, then another 45 to 60 days waiting on the buyer's mortgage. That is 68 to 83 days in total, for a house that was ready to show on day one. A cash sale skips both of those waits, because there is no lender to satisfy on the buyer's side. A short sale adds a wait of its own at the front, which is the servicer's review.
That ordering matters when a foreclosure sale date already exists. A cash sale can often be closed inside the window. A short sale usually needs the window extended, and servicers have discretion to adjourn when a credible contract is in front of them. Nobody can guarantee they will.
How selling a house in a short sale in Smithtown works
- 1
Tell us where it is
Just the address in 11787 and roughly what shape it is in. It takes a couple of minutes. Leave the house exactly as it is; we do not need it tidied, photographed or fixed.
- 2
A quick look in person
We visit once and it rarely takes more than half an hour. On the colonial or split-level houses that make up most of Smithtown, we check the roof, the boiler and the electric before anything cosmetic.
- 3
You get a number in writing
Within 24 hours, as a written figure rather than a range or a "starting around". Take it to a Suffolk County agent for a second opinion if you want to. On a house already in showable condition, listing may well beat us, and we would rather you knew that.
- 4
You choose when to close
Soon, or months away if probate, a tenant or your next move has to come first. You also avoid the 68 to 83 days a listed Smithtown house typically takes to find a buyer and get through the buyer's mortgage.
After the closing on a Smithtown short sale: what to ask about
The paperwork at the end of a short sale is where the real terms live. The approval letter says what the servicer will accept and, crucially, what it reserves the right to do about the rest.
Have an attorney read it. That single step is the most valuable thing most short sale sellers do, and it costs a fraction of what getting it wrong costs. We are glad to tell you what we typically see in these letters, but what applies to you is a legal question and belongs with your attorney. The tax treatment belongs with a CPA for the same reason.
What you do not pay when you sell a house in a short sale
These are the costs of putting a house in a short sale on the market through an agent. None of them apply when you sell to us.
- Agent commission
- $39,875 at 5% of the Smithtown median none
- Seller closing costs
- About $15,950 on a $797,500 sale. We can cover these. none
- Repairs to make it listable
- The work it needs to show well, out of your pocket first none
- Cleanout and removal
- Paid per load, before a single buyer walks through none
- Carrying costs while it waits
- Taxes, insurance and utilities while you spend 68 to 83 days finding a buyer and waiting for their loan none
The one call to make before choosing between a short sale and a cash sale
The worst outcome here is spending two months on the wrong route, and that happens when people guess at the payoff instead of asking for it in writing.
One call to the servicer settles half of it. One visit from us settles the other half. From there the choice between a short sale and a cash sale usually makes itself, and we will be straight with you about which one your Smithtown house is in.
Common questions
Do you handle short sales in Smithtown?
We do. A short sale is a different animal from an ordinary purchase, and we have taken plenty of them through to closing in Suffolk County. Tell us the payoff figure and where the file stands and we will tell you what we think.
How do I find out what I owe on the mortgage?
Ask the servicer for a written payoff statement. It is your right to have one and it takes a phone call. That figure, set against what the house is worth, is what decides between a short sale and a cash sale.
Can I do a short sale on a Smithtown house if foreclosure has already been filed?
A short sale and a foreclosure frequently run at the same time, and the short sale has to outpace the calendar. It can be done and we have been through it. Tell us where the Smithtown case stands, and speak to an attorney the same week.
Which is better for me, a short sale or a cash sale?
Whichever one your numbers permit. A cash sale is better in almost every respect except that it requires equity. If you are underwater, a short sale is not a worse choice, it is the available route, and it can still beat letting a foreclosure run its course.
Will I walk away with money from a short sale?
A short sale is about clearing the debt rather than producing proceeds. If there is equity, you are not in a short sale at all, which is the first thing worth checking. Get the written payoff before you assume it either way.