Why foreclosure timing matters more than anything else
New York foreclosures move slowly, which fools people into waiting. Every month a foreclosure runs, fees and interest get added to the payoff, and those come out of whatever equity you have rather than the lender's.
The same Smithtown house sold six months before the foreclosure sale frequently puts real money in the seller's pocket. Sold six months later, after the foreclosure costs have accrued, it often does not.
Working through Suffolk County foreclosures with you
Buying the house and paying the lender off at closing is the part everyone understands, and it does end the foreclosure. It is rarely the whole of what somebody in this position needs.
We have worked short sales across Nassau and Suffolk for years, sat through adjournments, and dealt with servicers who take three weeks to return a call. We bring in the attorneys and housing counselors we have used for years when a situation needs them, and we do that whether or not the house ends up being ours. Tell us where the Smithtown foreclosure has got to and we will tell you what your actual options are.
The Smithtown market underneath this
The Smithtown median has barely moved year over year as of 2026-05, at 1.27%. Flat is the hardest market to price a fixer into, because there is no upward drift to cover a mistake and no urgency pushing buyers to overlook a problem. A $797,500 median puts Smithtown in the band where buyers are stretching to afford the house and have nothing left for the roof. That is precisely the buyer who walks away from a property needing work, and it is why condition matters more here than the price alone suggests. The median house here goes under contract in about 23 days, which is quick for Long Island. It is also a figure that only applies to property in showable condition.
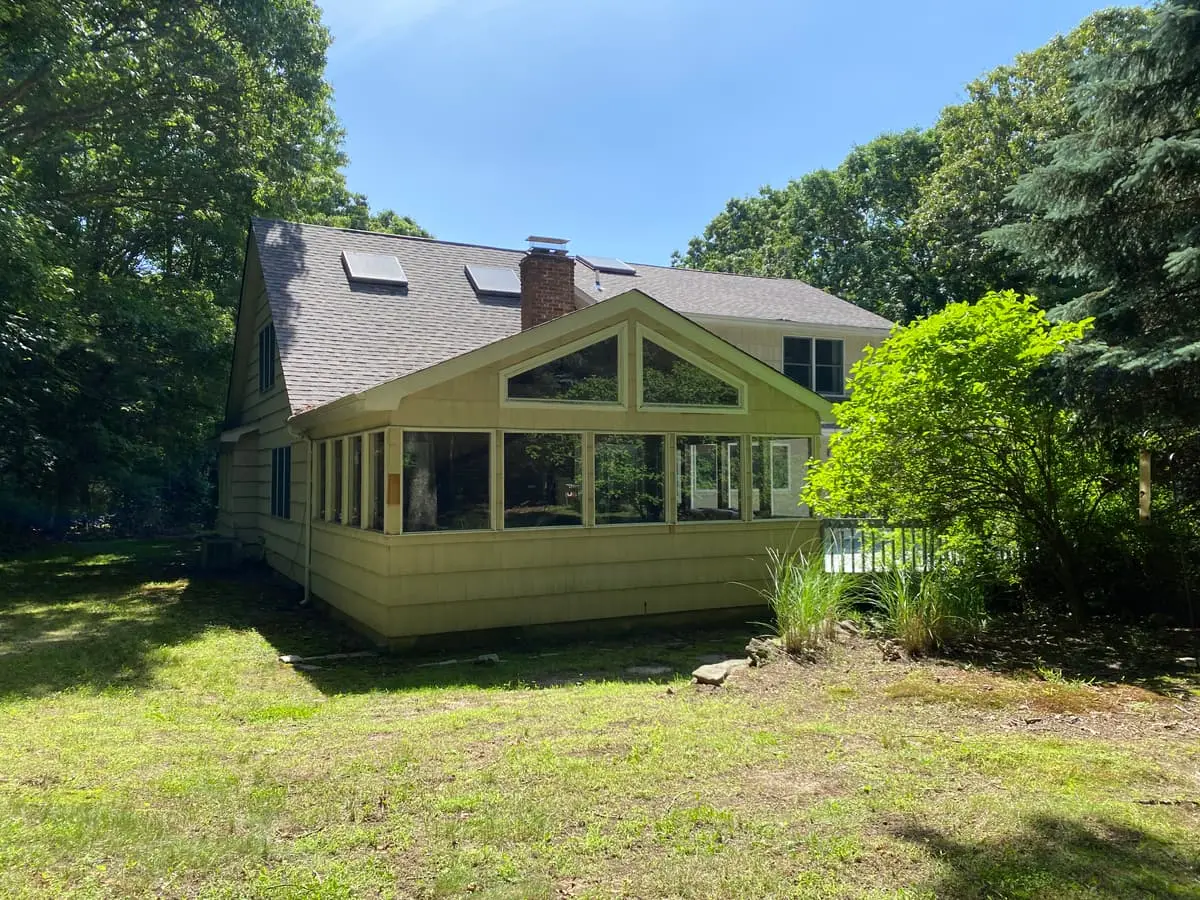
A house on Kent Place. In Smithtown, bought and paid for by us.
What an agreement to purchase does to the timeline
People assume a scheduled foreclosure sale is the end of the conversation. Frequently it is not.
With a signed agreement in hand, your attorney has something concrete to bring to the lender, and adjournments do get granted on that basis. We cannot promise the outcome because it is not our decision. What we can do is be the buyer who signs quickly and does not fall through, which is the whole of what makes such a request credible in a Smithtown case.
If you owe more than the Smithtown house is worth
The first thing to establish is the gap between the payoff and what a Smithtown house like yours actually sells for. Get the written payoff from the servicer; everything else follows from that number.
If there is equity, an ordinary sale protects it. If there is not, we can work a short sale with you, and we have taken plenty of them through to closing. Either way you will get a straight answer about which one you are looking at rather than a month of vagueness.
What the two paths cost in Smithtown
These are the two routes open to you with a house in foreclosure, priced against what Smithtown houses actually sell for.
Work it against Smithtown's own numbers. The median sale here is $797,500. A 5% commission on that is $39,875, and seller closing costs of about 2% add roughly $15,950. Those are costs we can cover on our side. That is $55,825 gone before anyone counts the repairs it took to get the house listable.
There are two waits in a listed sale and people usually only count the first. In Smithtown the median house takes about 23 days to go from listed to a signed contract. Then it waits again, typically 45 to 60 days, while the buyer's lender orders an appraisal and underwrites the loan. Call it 68 to 83 days from sign to keys, assuming nothing goes wrong.
The part worth understanding is what a signed contract actually guarantees, which is less than most sellers assume. A retail buyer with a mortgage contingency can walk away right up to the end. If they do not qualify, if the appraisal comes in under the price, if they change their mind and let the financing lapse. A share of deals die exactly there, after months of waiting, and the house goes back on the market with time on it. We are not borrowing anything, so there is no lender to satisfy, no appraisal to come in low and no contingency to exercise.
| Listing with an agent | Selling to us | |
|---|---|---|
| Sale price | $797,500 (Smithtown median) | Our written offer |
| Commission | −$39,875 | None |
| Seller closing costs | −$15,950 | We can cover them |
| Repairs before listing | Out of pocket | None |
| Cleanout | Yours | Ours |
| Showings | Until it sells | One visit |
| Listed to signed contract | 23 days (Smithtown median, once listable) | 24 hours to a written offer |
| Contract to closing | 45 to 60 days (waiting on the buyer's lender) | A date you choose |
| Total wait | 68 to 83 days if nothing falls through | Yours to set |
| Can the buyer walk? | Yes (mortgage contingency runs to the end) | No financing to fall through |
| Before repairs and carrying | $741,675 | The number we put in writing |
For the listing side we have used a 5% commission and about 2% in seller closing costs; your real figures may differ. Repairs and carrying costs are left out because they depend on the house. If yours is in good shape, a good agent may well get you more than we would, and we will tell you if so.
Keeping a Smithtown foreclosure private
Foreclosure filings are public record, which people find out at the worst possible time. What is not public is a private sale.
We do not list the property, photograph it for the internet, or put anything on the lawn. For most Smithtown owners in foreclosure, that discretion is worth as much as the timeline.
How selling a house in foreclosure in Smithtown works
- 1
Start with the basics
Where the house is (11787) and a rough sense of its condition is all we need to begin. Call or use the form. Nothing needs fixing or clearing out beforehand.
- 2
We come and look at it
One visit, one person, usually under half an hour. On a colonial or split-level of the age most of Smithtown was built, we are mainly looking at the roof, the boiler and the electric rather than the kitchen.
- 3
You see the number
Within a day you get our offer as one written figure. Get a Suffolk County agent's opinion alongside it if that helps. For a house that could go on the market as it stands, listing may come out ahead, and we will tell you if so.
- 4
Closing happens on your date
If you need it done quickly, it can be. If probate, a tenant or a move means waiting, we wait. What you skip is the 68 to 83 days a Smithtown listing usually spends on finding a buyer and then on that buyer's lender.
Equity, and how a foreclosure sale consumes it
Owners often assume a foreclosure wipes out their equity automatically. It does not, but the foreclosure process does consume it steadily, and an auction is rarely the venue where a house achieves its best price.
A sale you control, before the foreclosure completes, is the version where the equity is most likely to reach you rather than fund the costs of getting there.
Common questions
Is it too late to stop a Smithtown foreclosure once a sale date is set?
A scheduled foreclosure sale date does not always end the possibility of selling, but it compresses everything. We have closed Suffolk County purchases in that window. Get an attorney involved immediately alongside us.
Will I get any money out of a Smithtown foreclosure sale?
That depends on the payoff against what the house is worth. We will tell you honestly if the foreclosure has consumed the equity, rather than take you through a process that ends at zero.
Does selling my Smithtown house stop the foreclosure completely?
A sale that pays the mortgage off ends the foreclosure, yes. What it does to your credit record is a separate question and one worth asking an attorney or a credit counselor about.
Can you buy a Smithtown house once the foreclosure case has been filed?
Yes. A filed foreclosure does not prevent a sale in Smithtown, it simply adds a clock and some coordination between the attorneys. Tell us where the case stands and we will be straight with you about whether the timing works.